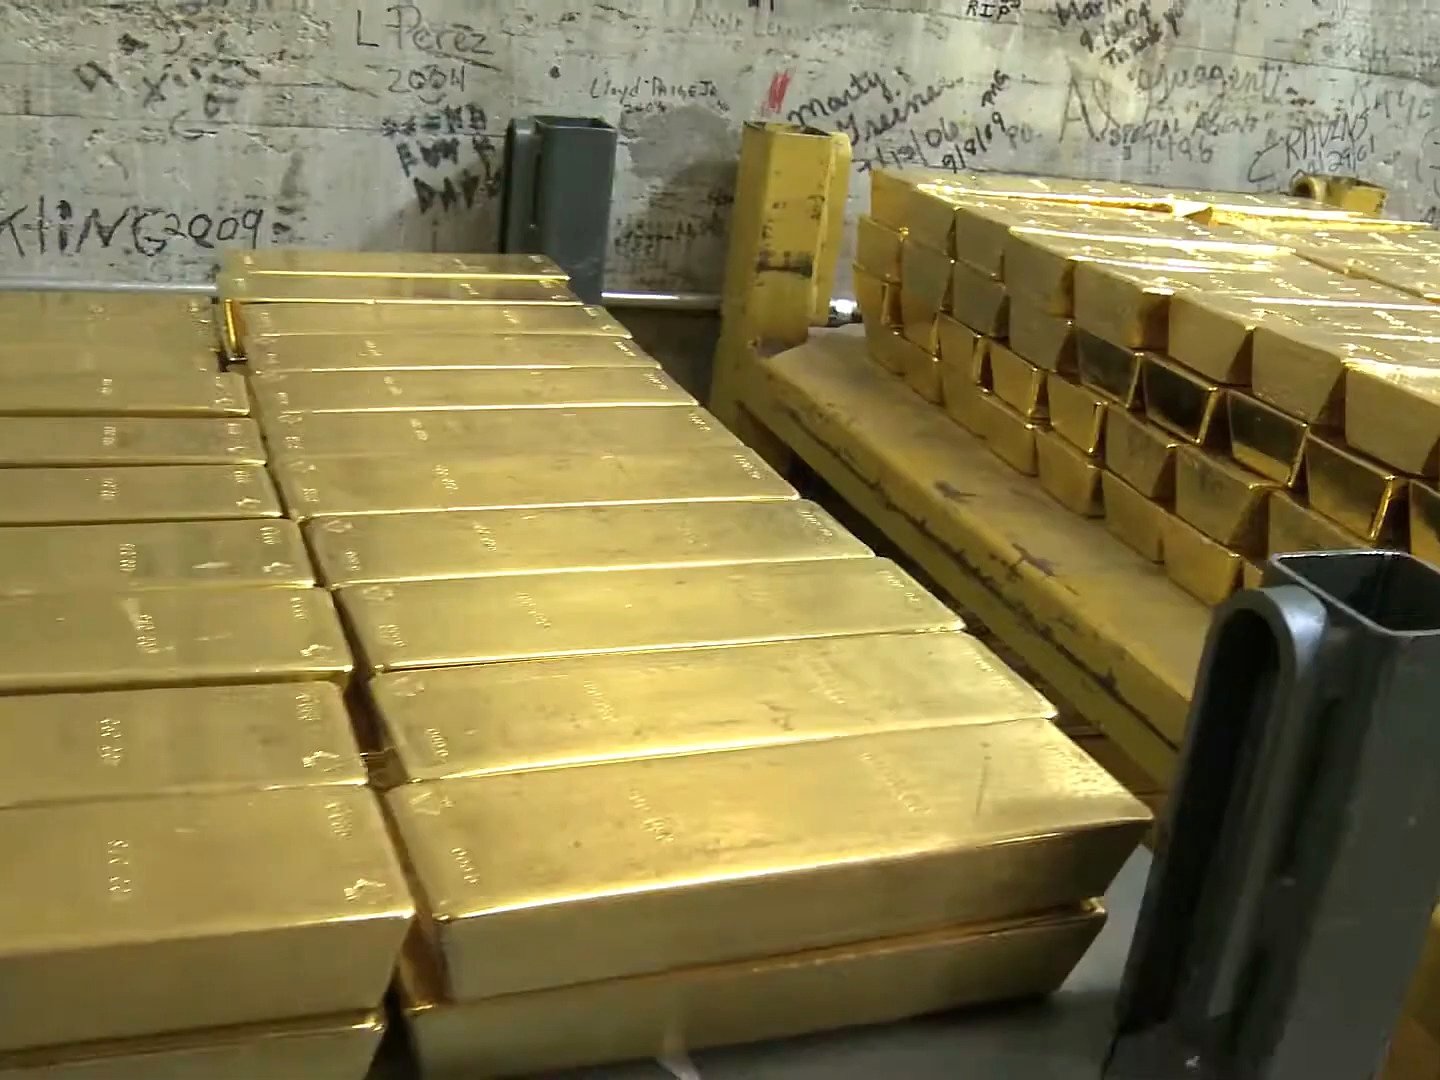
The gold vs bitcoin debate usually gets framed as old money against new, and that framing hides more than it explains. Both are pitched as hedges against the same thing: governments issuing more currency than the economy grows to support. In 2026 that thesis got a real test. Deficits ran near $2 trillion, federal debt pushed past $35 trillion, and the debasement argument was very much alive (CBO, February 2026 outlook). So which hedge actually did its job? The honest answer is that they did different jobs, and picking a single winner tells you more about your risk tolerance than about the assets.
The 2026 setup both assets were tested against
Gold came into 2026 hot and then broke. It hit an all-time high near $5,600 an ounce in January, then corrected hard. By mid-summer it traded around $4,050, off roughly 25% from that peak, after the worst gold quarter since 2013 when it fell 14.1% in Q2 (Kitco / Invesco, July 8, 2026). Ugly on the chart. But zoom out and gold was still up 21.3% over the trailing twelve months. A hedge that’s up a fifth on the year while making new lows off its high is doing something odd and important at the same time: it corrected without breaking the longer trend.
The macro driver of the drawdown wasn’t a failure of the debasement thesis. It was a hawkish new Fed under Chair Kevin Warsh, plus an energy-inflation shock out of the Strait of Hormuz that pushed real yields up and the dollar above 100 on the DXY. Non-yielding assets suffer when real yields climb. That pressure hit gold, and it hit bitcoin too. Which is the first thing worth saying plainly: in a rising-real-yield regime, neither of these is a magic escape hatch.
Gold vs bitcoin as a debasement hedge: the core trade-off
Gold offers a multi-century store-of-value record and a structural central-bank bid that bitcoin lacks, at the cost of lower upside. Bitcoin offers a fixed 21 million supply cap and larger potential gains, at the cost of far higher volatility and a shorter, thinner track record as a crisis hedge. That’s the trade in one paragraph.
Both assets share the property that matters for a debasement hedge: you can’t print more of them on political demand. Gold’s supply grows slowly through mining. Bitcoin’s is capped by code at 21 million coins. Neither is anyone’s liability. Where they split is on everything else, and the differences are large enough that calling them substitutes is lazy.
The property-by-property comparison
| Property | Gold | Bitcoin |
|---|---|---|
| Track record as store of value | Thousands of years | Roughly 17 years |
| Volatility | Moderate; a 25% drawdown counts as a rough year | High; drawdowns of that size are routine |
| Supply | Grows slowly via mining, no hard cap | Hard-capped at 21 million coins |
| Counterparty risk | None for physical metal | None for self-custodied coins; real if held on an exchange |
| Custody | Physical storage and insurance, or a vault | Private keys, or a third-party custodian/exchange |
| Institutional / official demand | Record central-bank buying | Growing fund and treasury interest; no central-bank reserve bid |
| Portability | Heavy, physical | Moves anywhere with a key |
The structural bid gold has and bitcoin doesn’t
Here’s the single biggest asymmetry between the two, and it gets underplayed by both camps. Central banks buy gold. They buy it in size, they buy it through corrections, and they say they intend to keep buying. The World Gold Council’s 2026 survey found a record 45% of central banks plan to raise their own gold reserves, and 89% expect global official gold holdings to rise over the next year (World Gold Council, June 16, 2026). The same survey found 74% expect the dollar’s share of reserves to decline. That is a price floor built from official-sector demand, and it kept bidding while Western ETF holders were selling into the drop.
Bitcoin has no equivalent. It has funds, some corporate treasuries, and a growing pool of institutional interest, but no central bank is accumulating it as a reserve asset. That’s not a moral judgment on bitcoin. It’s a structural fact about who’s on the buy side. When gold sells off, there’s a deep, price-insensitive buyer standing underneath it that bitcoin simply does not have.
Sprott’s Paul Wong summed up the force behind gold’s official-sector demand bluntly during the summer weakness: “That’s the heart of the debasement trade. It’s still on, it’s still there.” (Kitco, July 20, 2026.) The debasement case that drives gold buying is the same case bitcoin holders make. The difference is that one of the two has sovereign institutions acting on it with their balance sheets.
Volatility, correlation, and what “hedge” even means
The word hedge does a lot of hiding in this debate, so let’s be specific about what each asset hedges and how it behaves.
- Volatility profile. Gold’s 25% drawdown off its high was, by gold standards, a genuinely bad stretch, its worst quarter in over a decade. For bitcoin, a move of that magnitude is an ordinary quarter. If you can’t stomach 50%-plus drawdowns without selling, bitcoin’s volatility is not a footnote, it’s the whole experience.
- Correlation behavior. Bitcoin has often traded more like a high-beta risk asset than a safe haven, tending to sell off alongside risk when liquidity tightens. Gold’s behavior in crises has historically leaned the other way, though 2026 showed it’s not immune when real yields spike. Neither is a clean, all-weather negative correlation to stocks. Treating either as one will disappoint you at the wrong moment.
- Time horizon. Gold’s case rests on thousands of years of continuity. Bitcoin’s rests on roughly 17. The bull argument for bitcoin is that its record, though short, is enough to prove the design works. The bear argument is that it hasn’t lived through enough regimes to know how it behaves in all of them. Both can be true at once.
Custody deserves a line too, because it cuts differently than people expect. Physical gold carries no counterparty risk but is heavy and awkward to move. Bitcoin carries no counterparty risk if you hold your own keys, and it moves anywhere instantly, but self-custody puts the entire burden of security on you, and coins left on an exchange reintroduce exactly the counterparty exposure the asset was supposed to remove. The custody story for each is a genuine trade, not a clear win.
So which hedge worked?
We’re not going to hand you a personalized winner, because the honest answer depends on what you were hedging and how much volatility you could hold through. Frame it as trade-offs instead.
- If your hedge is meant to hold value through a crisis with limited drama, gold’s profile fits better. It corrected in 2026 without breaking its longer uptrend, it stayed up over twelve months, and it has a record central-bank bid underneath it. The cost is lower upside.
- If you’re hunting asymmetric upside and can genuinely tolerate deep drawdowns, bitcoin’s fixed supply and higher volatility offer more of both. The cost is a shorter track record, sharper crashes, and no official-sector buyer to lean on when it falls.
- If you believe the debasement thesis, which the $2 trillion deficits and $35 trillion-plus debt make hard to dismiss, notice that both assets are expressions of the same bet. Holding some of each is a coherent position, not a contradiction. They diversify each other because their risk profiles genuinely differ.
The lazy version of this debate treats it as a team sport. The useful version treats gold and bitcoin as two tools built for overlapping problems with different failure modes. Gold trades upside for a longer record and a structural bid. Bitcoin trades that record and that bid for higher volatility and higher potential reward. Decide which failure mode you can live with, size accordingly, and skip the tribalism. For where we think gold goes from here, see our gold price forecast for 2026, and if you want the mechanics of adding metal, start with how to buy gold.
Frequently asked questions
Is gold or bitcoin the better inflation hedge?
They hedge the same idea differently. Gold has a multi-century record and a record central-bank bid but lower upside. Bitcoin has a fixed 21 million supply and larger potential gains but far higher volatility and a much shorter history. Neither escapes rising real yields, as 2026 showed when both came under pressure.
Why do central banks buy gold and not bitcoin?
Gold has served as an official reserve asset for centuries and carries no counterparty risk in physical form. The World Gold Council’s 2026 survey found a record 45% of central banks plan to add gold. No central bank accumulates bitcoin as a reserve, so gold has a structural sovereign bid that bitcoin currently lacks.
Did gold or bitcoin perform better in 2026?
Gold fell about 25% from its roughly $5,600 January high yet was still up 21.3% over the trailing twelve months by mid-year. We’re not publishing a specific bitcoin price here. The broader point stands: gold corrected without breaking its longer uptrend, while bitcoin’s swings in either direction tend to be larger.
Can I hold both gold and bitcoin?
Yes, and many investors who accept the debasement thesis do. Because their volatility and risk profiles differ, they diversify each other rather than duplicate. Holding some of each is a coherent way to bet on currency debasement without concentrating in one asset’s failure mode.
Which has less counterparty risk, gold or bitcoin?
Physical gold has none once you hold it. Bitcoin has none if you self-custody your keys, but coins left on an exchange carry real counterparty risk. Gold’s custody is physical and awkward; bitcoin’s is digital and puts security entirely on the holder. Each is a genuine trade-off.
By the Commodities Unfiltered desk. Last updated July 2026.
This is market analysis, not investment advice.
Leave a Reply